ASK SANDY MARGOLIN - CERTIFIED AI AGENT Realtor - Former Appraiser - Las Vegas
National Agent Referral

Resources

Start here Resources Hub The full library of Las Vegas guides, tools, checklists and calculators, organized the way real decisions happen. Explore the Hub Lifestyle first Neighborhood Guides Lifestyle-first looks at Las Vegas communities, so you can picture the neighborhood before you visit it. Explore the Guides MOVING? START HERE Relocation Guides Step-by-step guides for relocating from Las Vegas to cities across the country. Explore the Guides 55+ living 55+ Guides Active-adult and 55+ communities across Las Vegas and Henderson, compared on lifestyle first. Explore the Guides New homes New Construction New-home guides for Las Vegas buyers, including why your own agent matters at the model home. Explore the Guides Money Lenders and Financing Loans, pre-approval and rate questions in plain English, plus the calculators that make the math real. Explore the Guide To-dos Moving Checklists Before you fly, during the research trip and moving week: the practical lists so nothing slips. See the Checklists Market data Market Reports How to read Las Vegas market data and what the indicators actually mean for your decision. Explore the Reports Tools Calculators Mortgage, affordability, neighborhood comparison and cost-of-living tools that run entirely in your browser. Use the Tools Articles Blog Practical articles answering the Las Vegas real estate questions buyers and sellers actually ask. Read More Eat well Dining Guide Where to eat around Las Vegas, from locals' staples to the tables worth the drive across the valley. Explore the Guide The agent About Sandy 36-plus years in real estate, former appraiser, Certified AI Agent. The experience behind the answers. Learn More For sale Listings Current Las Vegas homes for sale, with community context so you know what each area offers. View Listings Current Market Report What the Las Vegas market is doing right now, without the hype. Read More Reviews Reviews What past clients say about buying and selling with Sandy across the Las Vegas Valley. Read More Answers FAQ Straight answers to the questions buyers, sellers and relocating families ask before they call. Read More
Recommended lenders

Lenders and Financing

These are the two lenders I send my clients to. I recommend them because they answer the questions that matter, explain the numbers in plain English and follow through after the offer is accepted. Apply with either one directly, and I stay in the room for the whole conversation.

Sheila Merrill headshot

Sheila Merrill

The Lending Lady

NEO Home Loans

Known as The Lending Lady, she is a Las Vegas mortgage professional who guides clients through smooth, stress-free home financing.

Visit Facebook
Buyer Guide · Financing


Before any house shopping begins, the financing has to make sense. This page explains pre-approval, the common loan programs, what drives your rate and the monthly math most buyers forget to include.

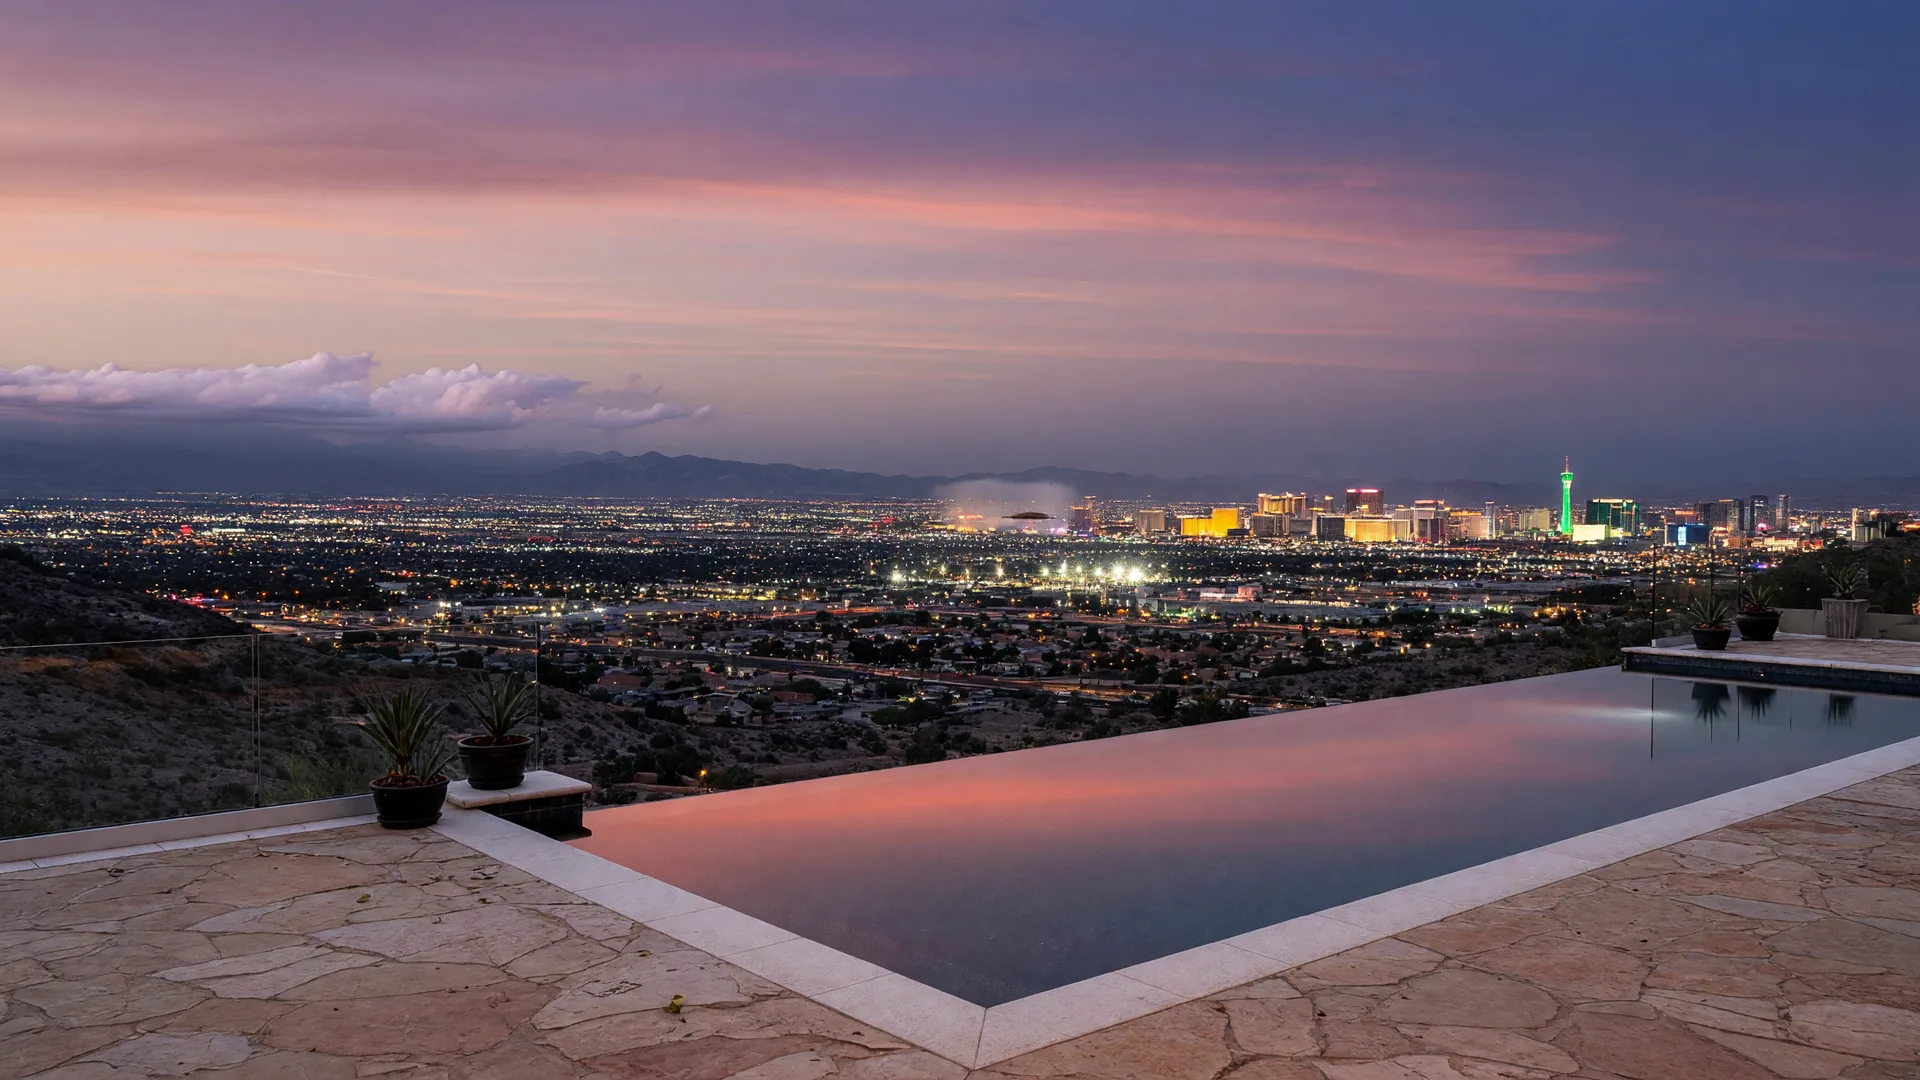
Las Vegas valley at dusk
01 · The basics

Pre-approval versus pre-qualification

Pre-qualification is a rough estimate based on what you tell a lender. Pre-approval is a real underwriting step: the lender verifies your income, assets and credit and commits to a loan amount.

In a competitive market, pre-approved buyers negotiate from a different position. Sellers' agents know the difference, and so should you.

02 · Loan programs

The common loan programs in Nevada

Conventional loans work for most buyers and offer low down-payment options. FHA loans allow lower down payments and easier credit standards. VA loans serve qualifying veterans and active-duty buyers with zero down. USDA loans cover eligible rural areas. Jumbo loans handle purchases above the conforming limit, which matters in luxury markets like Summerlin's upper price points.

Nevada also has state programs through the Nevada Housing Division, including down payment assistance for qualifying first-time and repeat buyers. I keep current on what is available and connect you with lenders who know these programs inside out.

03 · The rate

What actually drives your rate

Credit score, loan type, down payment, loan size and market conditions all move your rate. Points (prepaid interest) can buy a lower rate if you plan to stay long enough for the savings to pay back.

Rate shopping matters: comparing offers from a few lenders on the same day usually costs nothing and can save real money over 30 years. I can name the lenders I send clients to and why.

04 · The math

The monthly math nobody puts on the portal

Principal and interest are only part of the payment. Add property taxes, homeowners insurance, and HOA dues, which in Las Vegas master-planned and 55+ communities can be significant and vary wildly by community.

Use my mortgage and affordability calculators under Resources to see the full number, then confirm it with your lender's official estimate before you make an offer.

Nevada has no state income tax, one of the reasons homeownership math here looks different than in California. Your lender's estimate should reflect local tax and insurance realities, not a generic national guess.

05 · Lender questions

Questions to ask any lender

"What rate and points am I actually being quoted?" "Are the taxes and insurance in this estimate real numbers for this address?" "How long is this pre-approval valid, and does it survive a job change?" "Will this loan work for HOA-heavy communities, condos or high-rises?"

A lender who answers those clearly earns the business. I send clients to lenders who do, and I stay in the room for the whole conversation.

Straight answers

Questions before the call

How much down payment do I need in Las Vegas?

Conventional loans can go as low as around 3%, FHA around 3.5%, VA and USDA as low as zero for those who qualify. The bigger question is what leaves you comfortable after closing, and we model that before you pick a program.

Should I lock my rate before I find a house?

A rate lock holds a rate for a set period, typically 30 to 60 days, so you can lock when you are close to an offer. Your lender can advise on lock timing as the market moves.

Can I buy with less-than-perfect credit?

Often yes, through FHA or specialized programs, sometimes with a higher rate or a required repair conversation. The honest answer depends on your full credit picture, which the lender reviews in the pre-approval.

Do HOA dues count against my loan?

Yes. Lenders include HOA and condo dues in your debt-to-income calculation, and some condo and high-rise buildings face additional lender requirements. That is part of why community selection comes before the offer, not after.

Want the answer for your situation?

Guides answer the general question. The phone call answers yours, with your numbers.

Ask for yours